Bonus Study · Edition 01
The UK Casino Bonus Study, October 2026
Nearly nine months after the Gambling Commission capped bonus wagering at ten times, we read every welcome offer at 128 UK casino brands and counted what is actually in them. The short version: trading brands show smaller headline numbers and fairer terms than the brands that left.
- 128 (Brands measured)
- 297 (Offers read)
- 10x (Median wagering)
- 98% (Within the cap)
- 53% (Spins wager-free)
- Edition: 01
- Data snapshot: 5 October 2026
- Sample: 128 UK brands
- Source: Casino.net operator database
 Author: Casino.net Research Team
- Every figure here is frozen at the snapshot date and is not maintained afterwards. Later editions carry their own date and their own numbers. For offers you can claim today rather than a picture of the market, see our best online casino UK ranking.
On 19 January 2026 a single line in the Gambling Commission’s licence conditions changed how a UK casino bonus can be built. SR Code 5.1.1(3a) caps wagering requirements at ten times the bonus amount, full stop, for every operator holding a British licence. The same change banned offers that mix betting, casino, bingo and lottery into one wagering pot.
Rules like that get announced, reported and then quietly forgotten. Nobody goes back a year later to check whether the offers on the shelf actually changed. That is what this page is: not a list of bonuses to claim, but a measurement of the whole UK shelf on a single day, so that next year we can measure it again and see which way it moved.
We read 297 welcome offers: 148 at brands still trading in Britain, 124 at brands that have since closed or been removed, whose last recorded terms are still on file, and 25 at brands with no affiliate account or no recorded status, which sit outside both groups. Where a number is missing from our database we say so rather than guessing; a gap in our records is a gap in what we hold, not proof the operator withholds it.
Trading Brands Versus Exited Brands
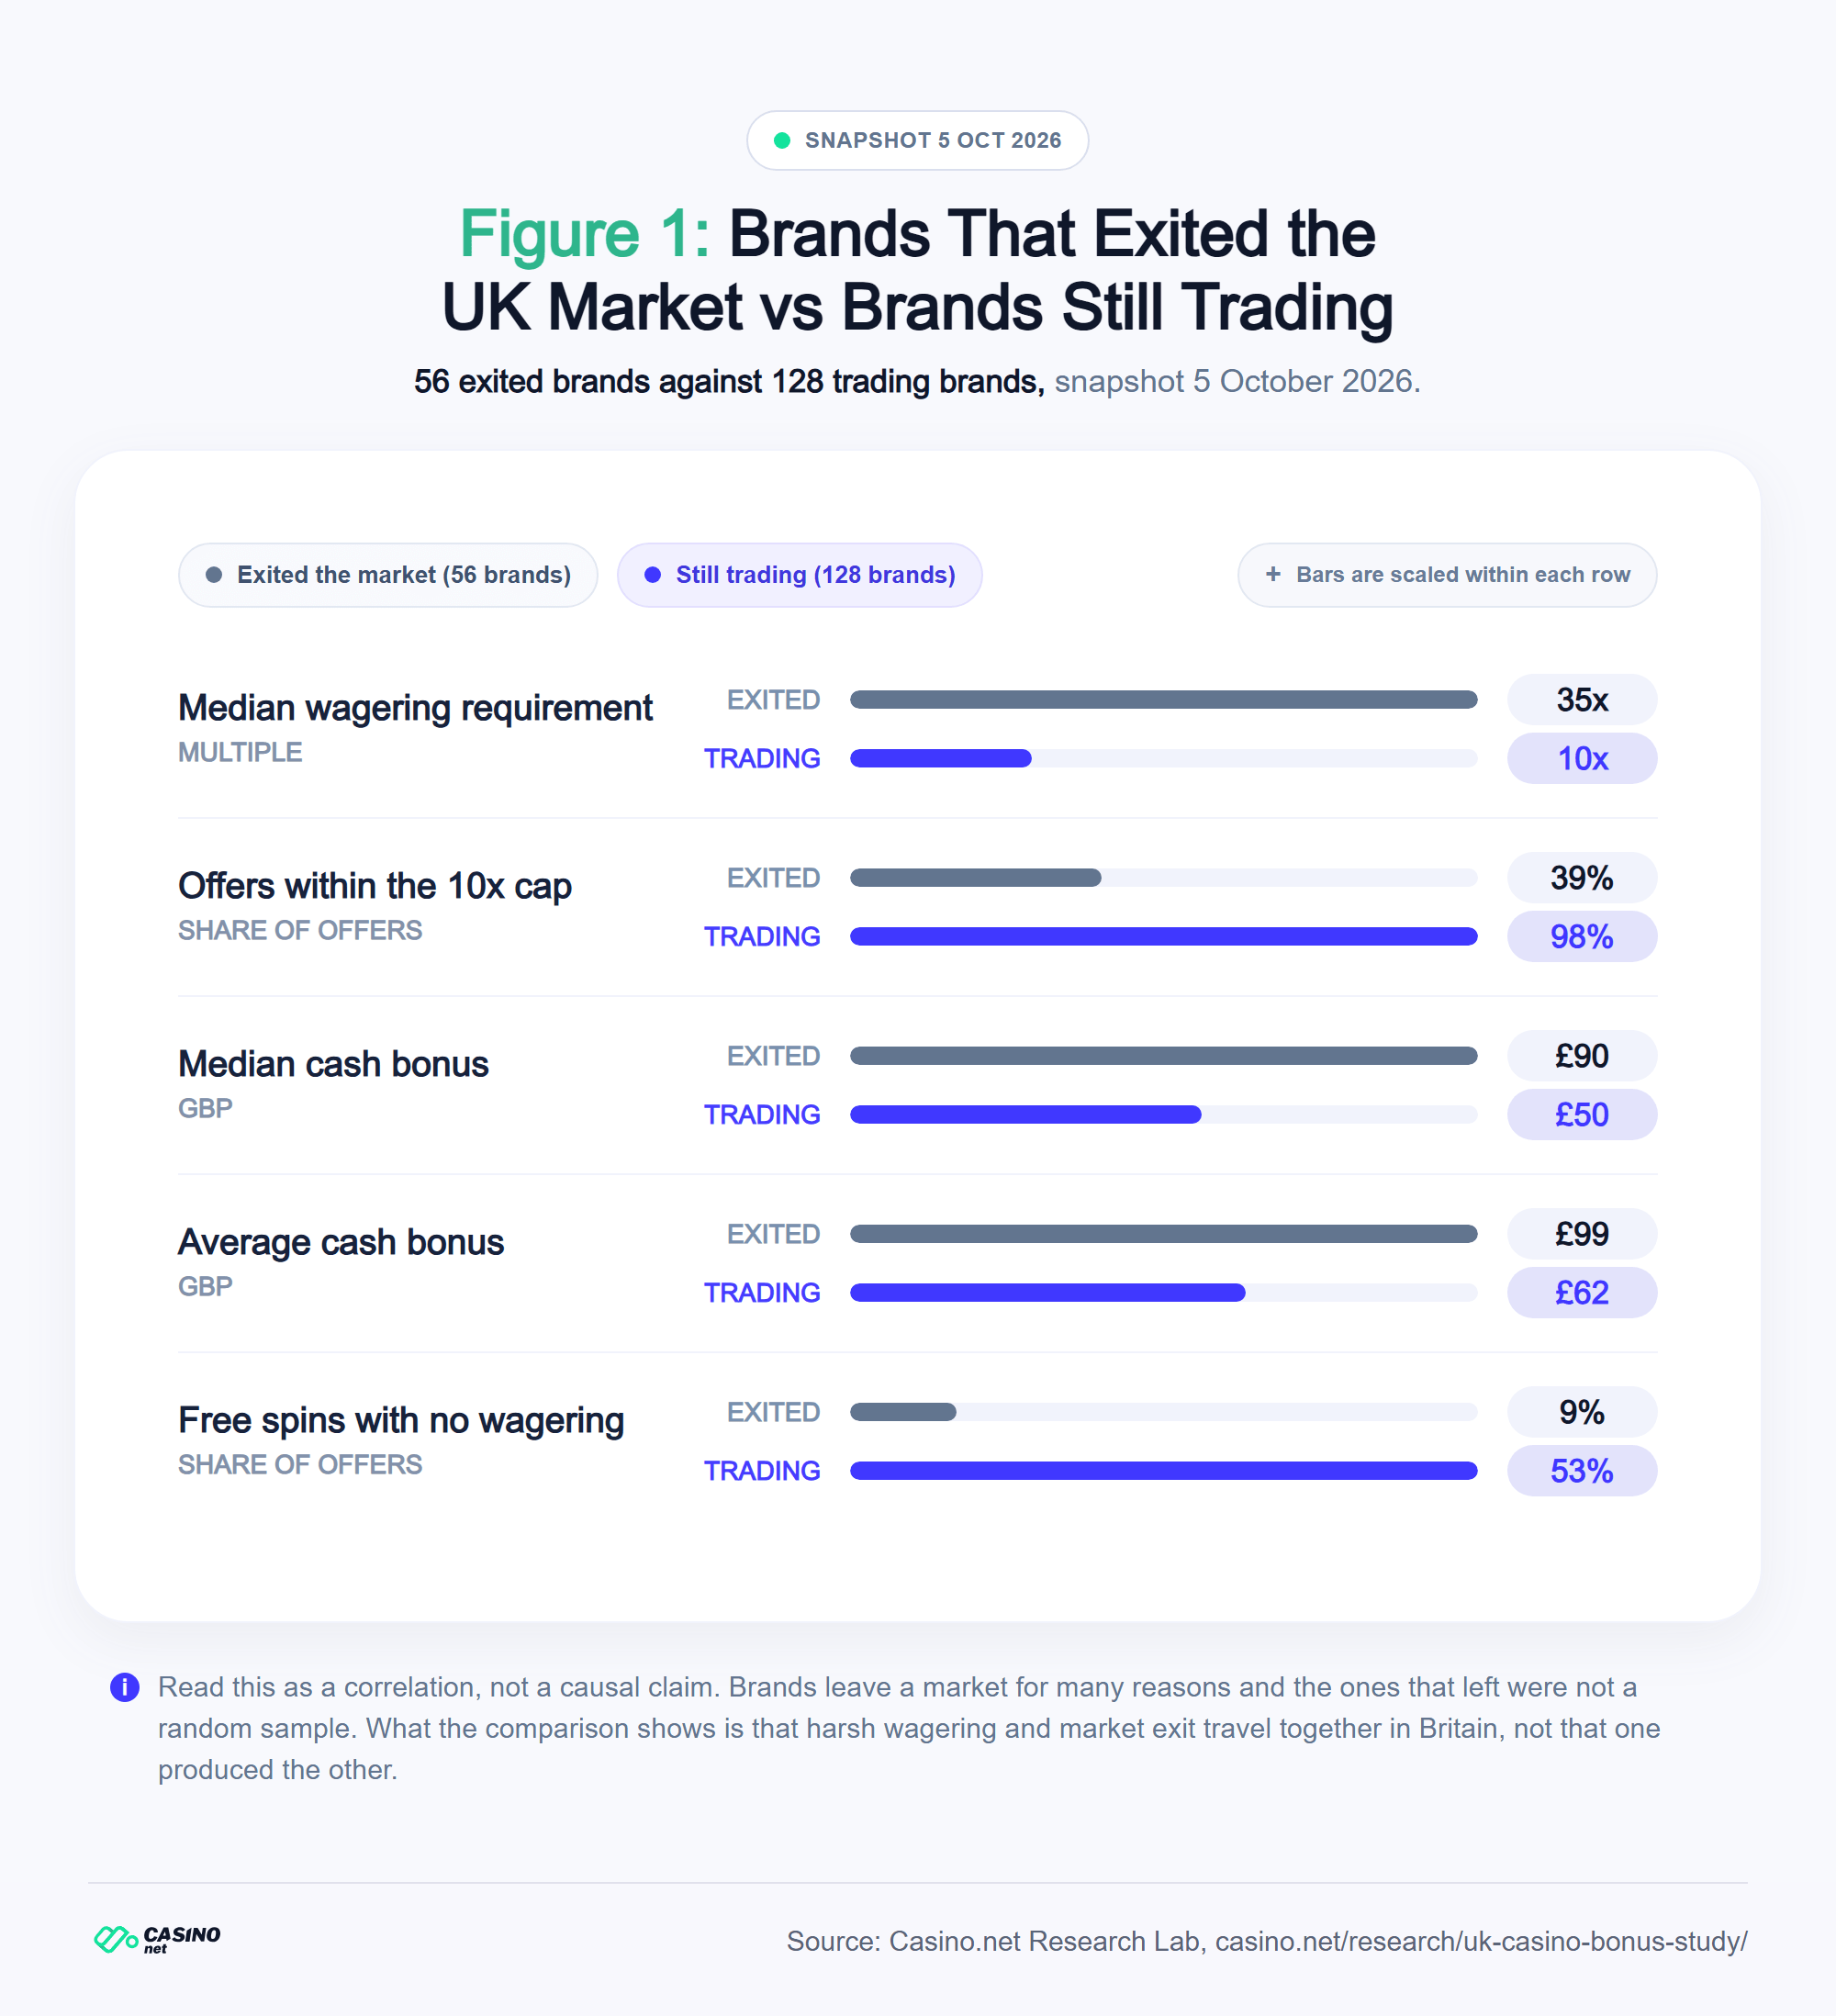
The exited cohort’s median wagering requirement is three and a half times the trading cohort’s.
We cannot rewind a single operator’s terms to 2025, because our records hold what an offer is rather than what it was. We therefore compare two separate groups: brands still trading and 104 UK market entries marked closed, 56 of which still carry usable offer terms. This is a cohort comparison, not a time series or a before-and-after sample.
Snapshot 5 Oct 2026
Figure 1: Brands That Exited the UK Market vs Brands Still Trading
56 exited brands against 128 trading brands, snapshot 5 October 2026.
- Median wagering requirement (Multiple): Exited: 35x, Trading: 10x.
- Offers within the 10x cap (Share of brands’ headline offers): Exited: 39%, Trading: 98%.
- Median cash bonus (GBP): Exited: £90, Trading: £50.
- Average cash bonus (GBP): Exited: £99, Trading: £62.
- Free spins with no wagering (Share of brands’ headline offers): Exited: 9%, Trading: 53%.
Read this as a correlation, not a causal claim. Brands leave a market for many reasons and the ones that left were not a random sample. What the comparison shows is that harsh wagering and market exit travel together in Britain, not that one produced the other.
Read side by side, the two groups barely look like the same industry. The median exited brand has a recorded 35x requirement; the median trading brand asks for 10x. The mean gap is wider still, 50x against 6x, because the exited cohort has a long tail of 35x, 65x and 200x offers with no equivalent in the trading cohort.
If the cap influences offer design, one possible commercial response is a smaller prize. In this snapshot, the trading cohort’s offers are smaller than the exited cohort’s: median cash £50 versus £90, and mean cash £62 versus £99. Cash appears in 27% of trading brands’ headline offers and 57% of exited brands’ offers.
Then the number we did not expect. Among exited brands, 9% of free-spin offers have no wagering attached; among trading brands, 53% do. Wager-free spins are a majority in the trading cohort and a rarity in the exited cohort. A smaller bonus you can withdraw is more usable than a large one you cannot, but this comparison does not show how any individual brand changed.
What the Cash Bonus Looks Like
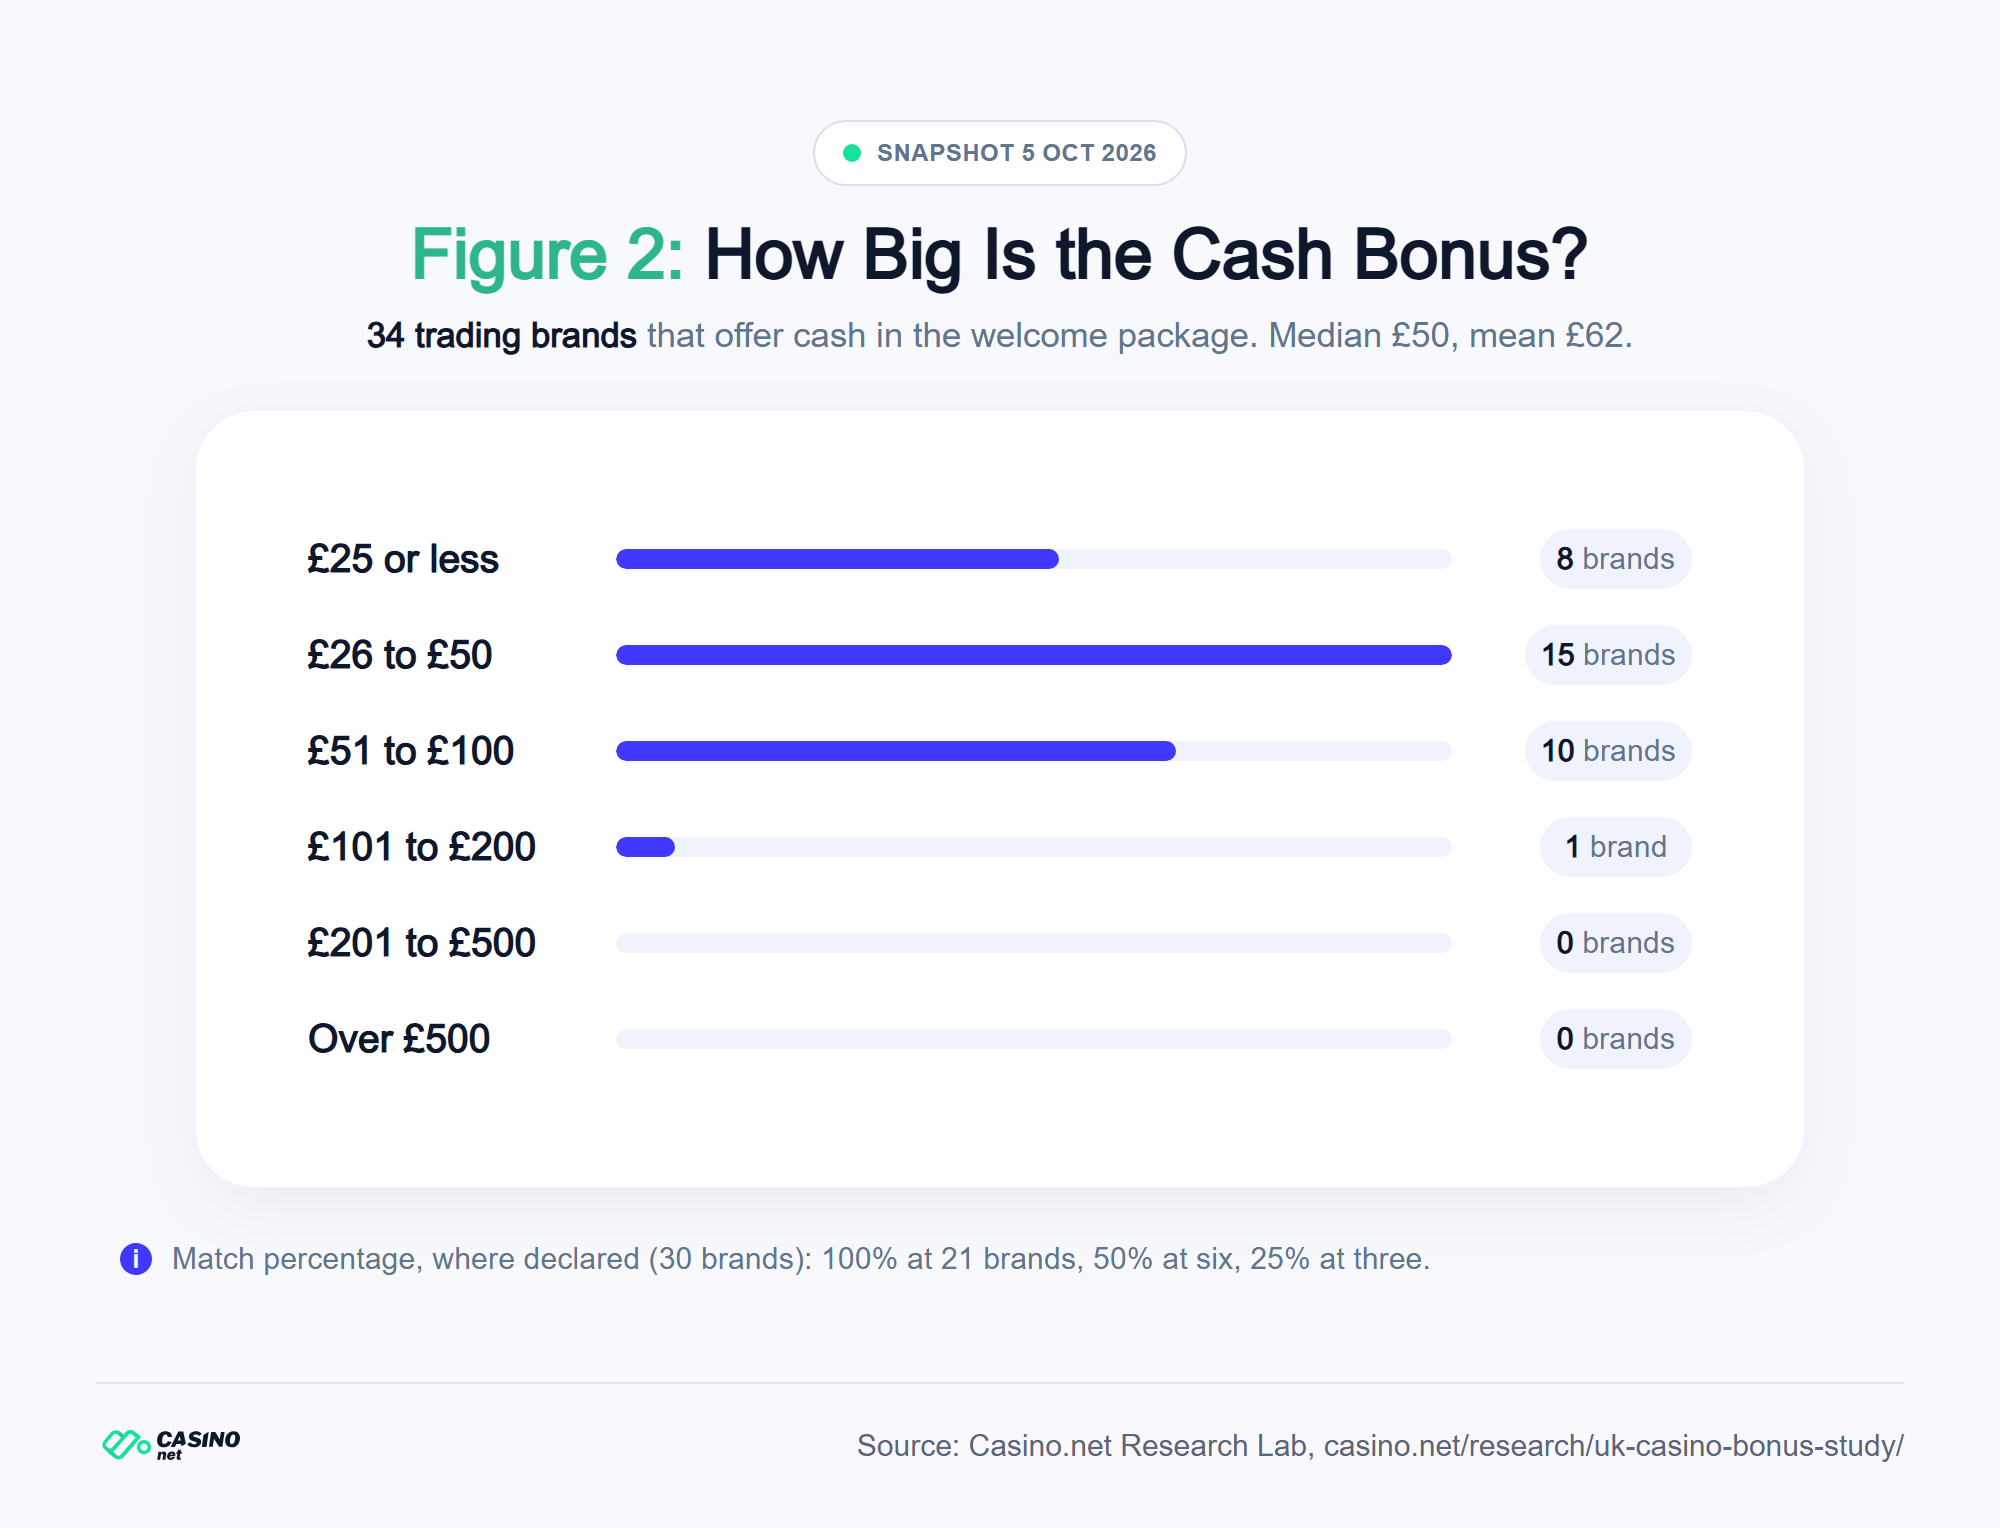
Only 34 of the 128 trading brands put cash in the welcome offer. Here is how much, and on what terms.
Cash bonuses in Britain are small and cluster low. Three quarters of the cash offers we read sit between £26 and £100, and the most common shape is a 100% match: of the 30 brands that publish a match percentage, 21 match your deposit pound for pound. Fifty percent matches are a distant second at six brands, and no brand matches at 200%.
Snapshot 5 Oct 2026
Figure 2: How Big Is the Cash Bonus?
34 trading brands that offer cash in the welcome package. Median £50, mean £62.
Match percentage, where declared (30 brands): 100% at 21 brands, 50% at six, 25% at three.
The tails have all but gone. Exactly one trading brand offers more than £100, a £200 match at 10x, and nothing in the market goes above it. At the other end, eight brands cap the cash at £25 or less, and every one of them still carries 10x wagering, so a small number is no longer a sign of a wager-free offer.
The most useful way to read this section is against the next one. A cash bonus is the part of the offer that comes with the wagering attached; the spins are increasingly the part that does not.
Free Spins Lead Trading Offers
111 brands give spins. Only 34 give cash. And 91 brands offer spins without cash.
If you only looked at the cash figure, you would miss the shape of the trading cohort. Free spins appear in 87% of trading brands’ headline offers and cash in 27%, while seven in ten offer spins without cash. Twenty brands run both together, 14 are cash-only, and three give neither and lead on something else.
Snapshot 5 Oct 2026
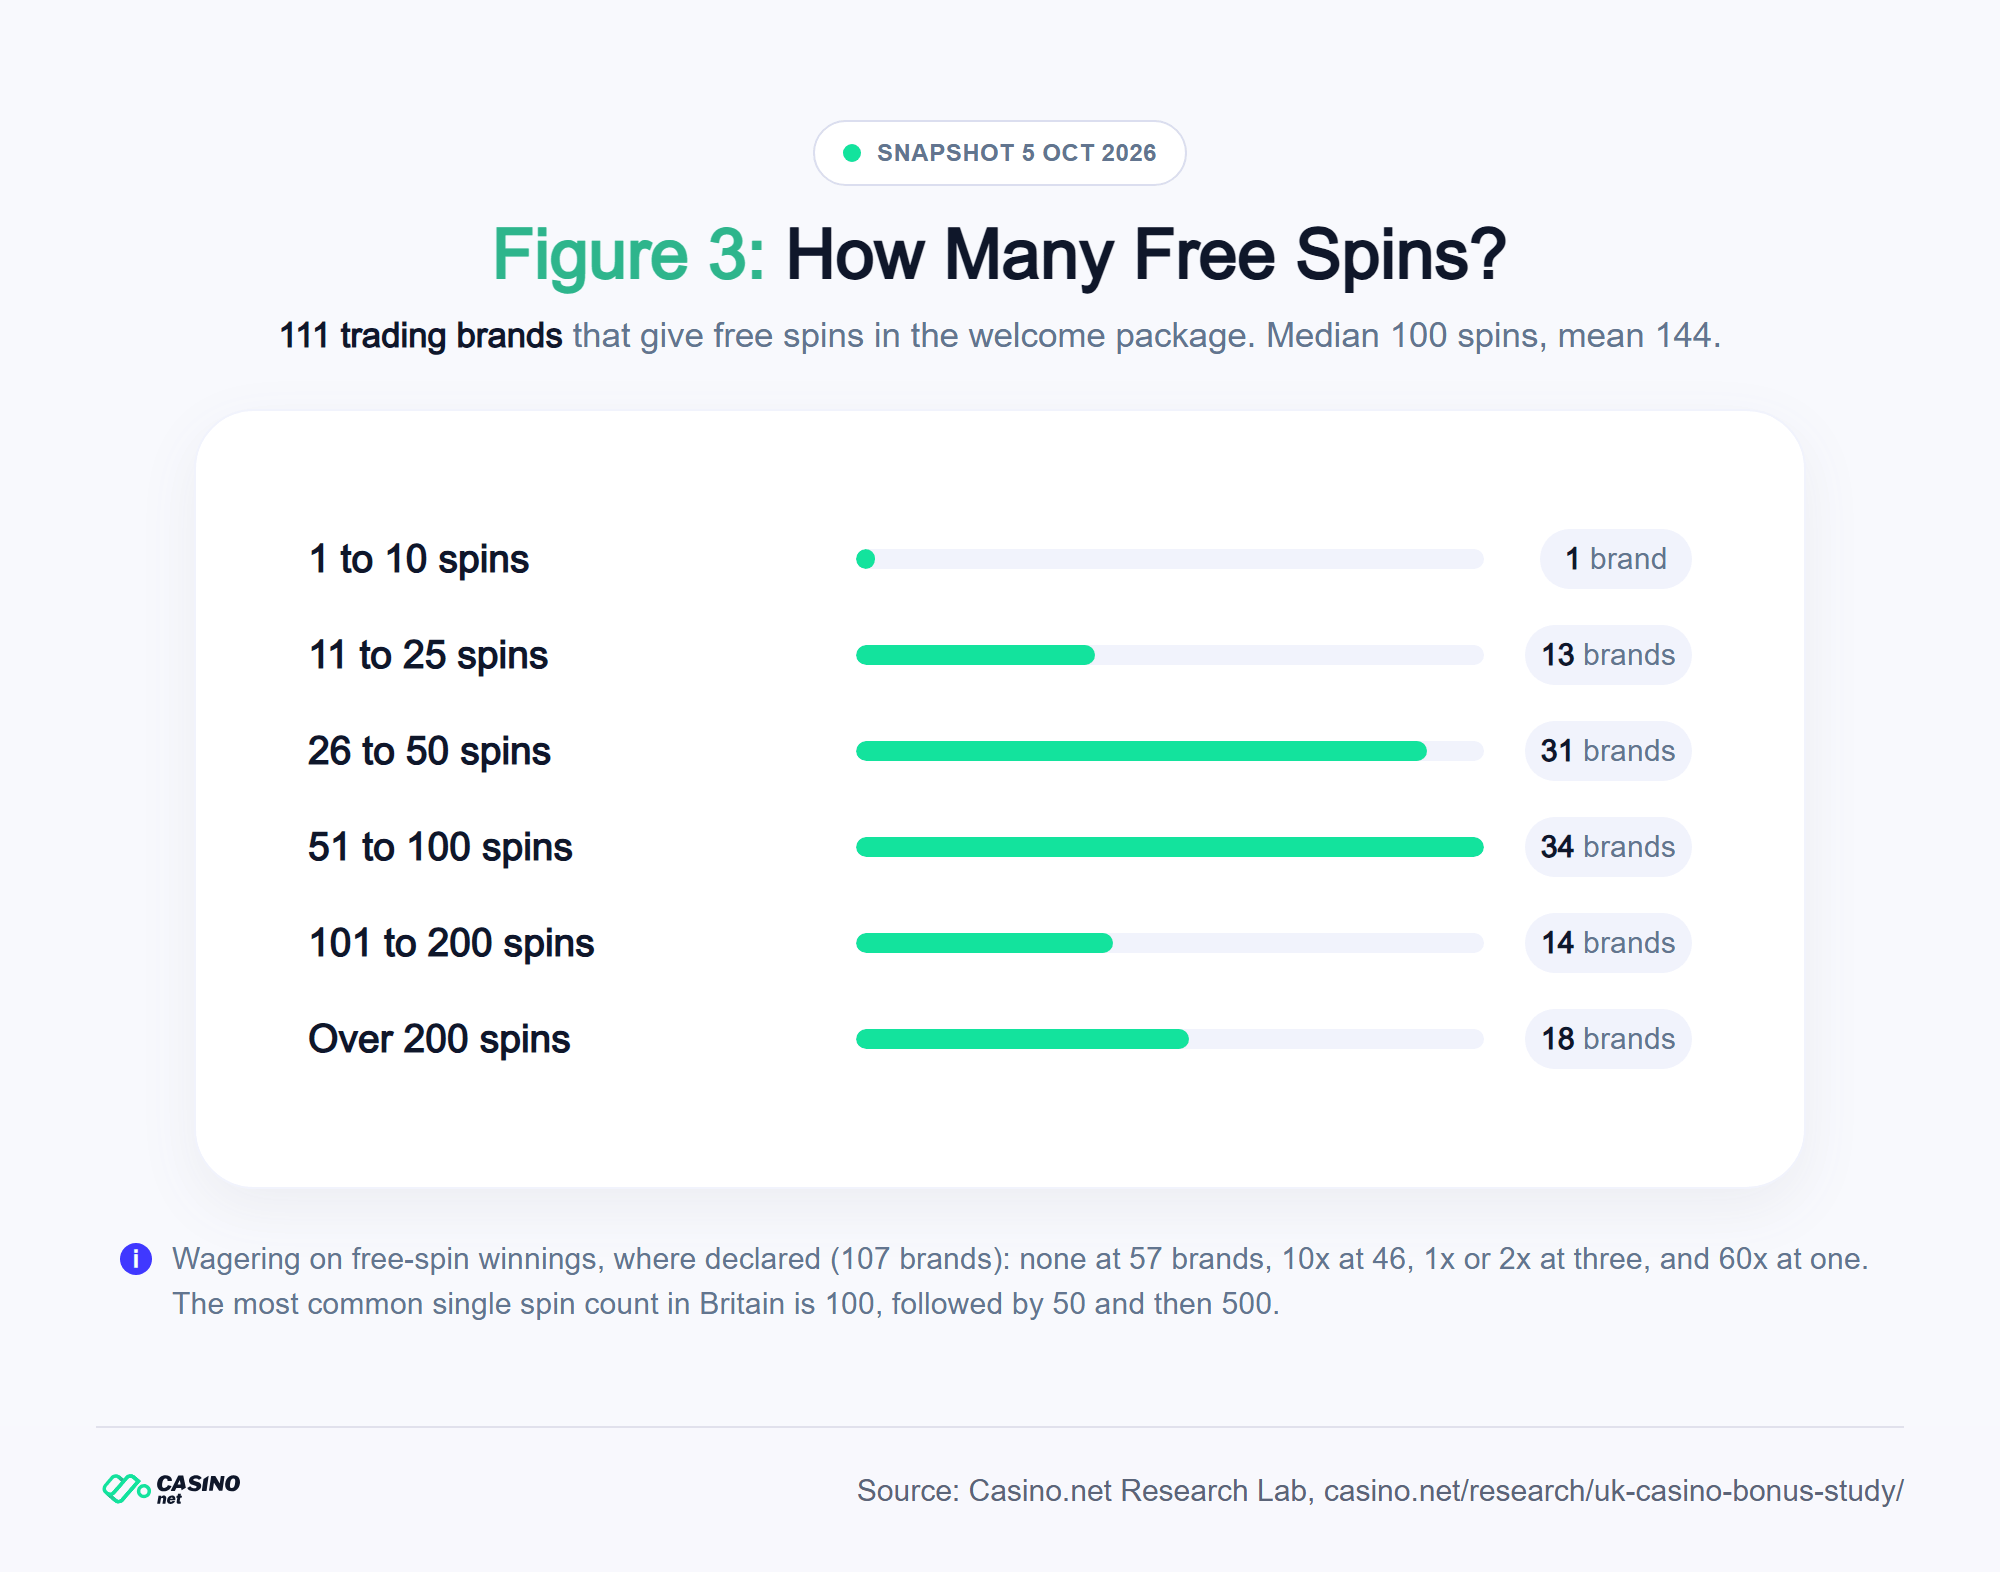
Figure 3: How Many Free Spins?
111 trading brands that give free spins in the welcome package. Median 100 spins, mean 144.
Wagering on free-spin winnings, where declared (107 brands): none at 57 brands, 10x at 46, 1x or 2x at three, and 60x at one. The most common single spin count in Britain is 100, followed by 50 and then 500.
The typical package is 100 spins, but the spread is far wider than on the cash side and its shape is telling. Brands that give spins and cash hand out a median of 50 spins; brands that offer spins without cash give a median of 100, twice as many, so the spins carry more of the offer. Eighteen brands go past 200, and sixteen of those land on the same round number of 500.
Then the finding that matters most to anyone actually claiming one. Of the 107 brands that state what free-spin winnings are worth, 57 attach no wagering at all: what you win is cash, and you can withdraw it. Another 46 apply 10x. One recorded offer asks for 60x on free-spin winnings. Free spins are a bonus, and when the winnings become bonus funds that require wagering before withdrawal, the 10x cap applies. If those terms were current on the snapshot date, 60x exceeded the cap; the record may instead have been stale.
20 brands
Give cash and spins together,
16% of the market.
91 brands
Give spins only and no cash at all,
71% of the market.
14 brands
Give cash only and no spins,
11% of the market.
3 brands
Give neither and lead on something else,
2% of the market.
Almost Every Brand Sits Under the Cap
The legal ceiling has become a magnet: 10x is not just the limit, it is by a distance the most popular number in the market.
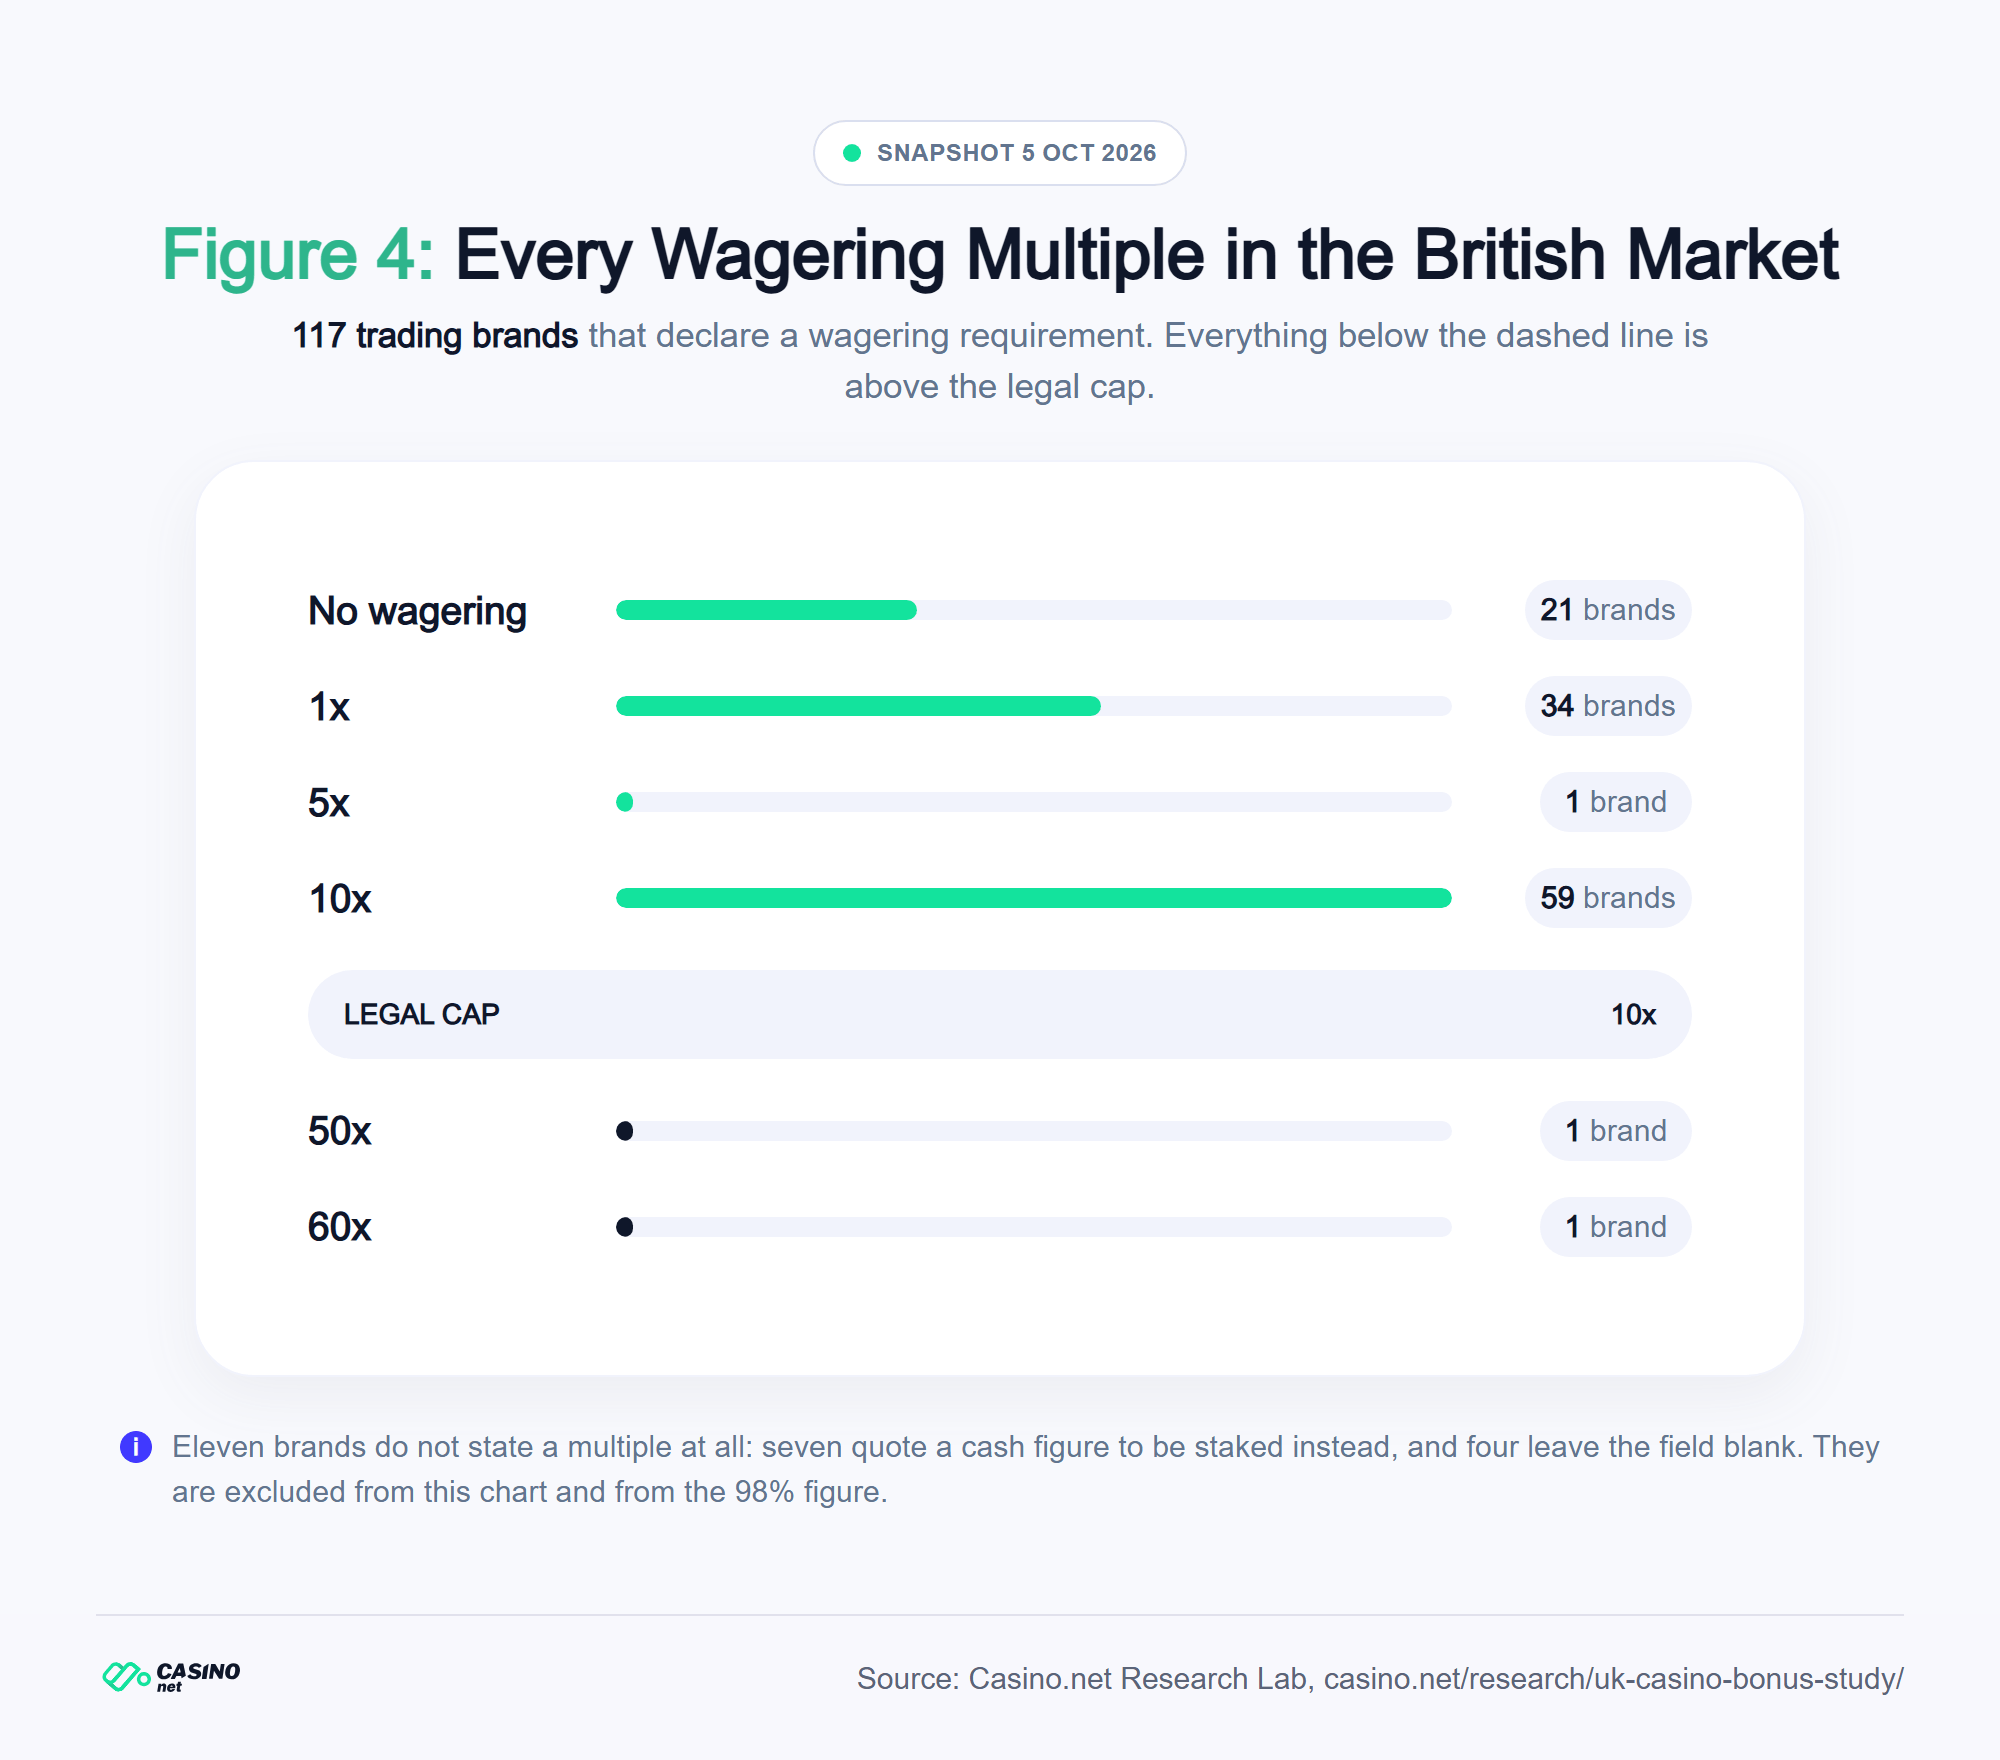
Of the 117 trading brands that state a wagering requirement, 115 are at or under 10x and 59 of them sit exactly on it. Another 34 ask for just 1x and 21 ask for nothing at all. Between 2x and 9x there is one brand in the entire British market.
Snapshot 5 Oct 2026
Figure 4: Every Wagering Multiple in the British Market
117 trading brands that declare a wagering requirement. Everything below the dashed line is above the legal cap.
Eleven brands do not state a multiple at all: seven quote a cash figure to be staked instead, and four have no value recorded. They are excluded from this chart and from the 98% figure.
The cohort comparison is consistent with what a cap would do. In the exited cohort, recorded wagering requirements range from 30x to 200x. Among trading brands they cluster in three positions: nothing, once, or the maximum the law allows. The main differences among trading offers lie in the spins and the small print.
Two brands still show a figure above 10x, one at 50x and one at 60x. We are deliberately not naming them, because a figure above the cap can mean one of two very different things, a licensee in breach or a stale record on our side, and because any list of names on a dated page would be wrong within weeks. Earlier readings showed more. Our team checked those records against the operators’ own published terms in September and corrected the ones that had gone stale; the two that remain are queued for the same check.
Lower Wagering, Smaller Spins
This is the finding we did not go looking for, and it hides underneath the number everybody actually compares.
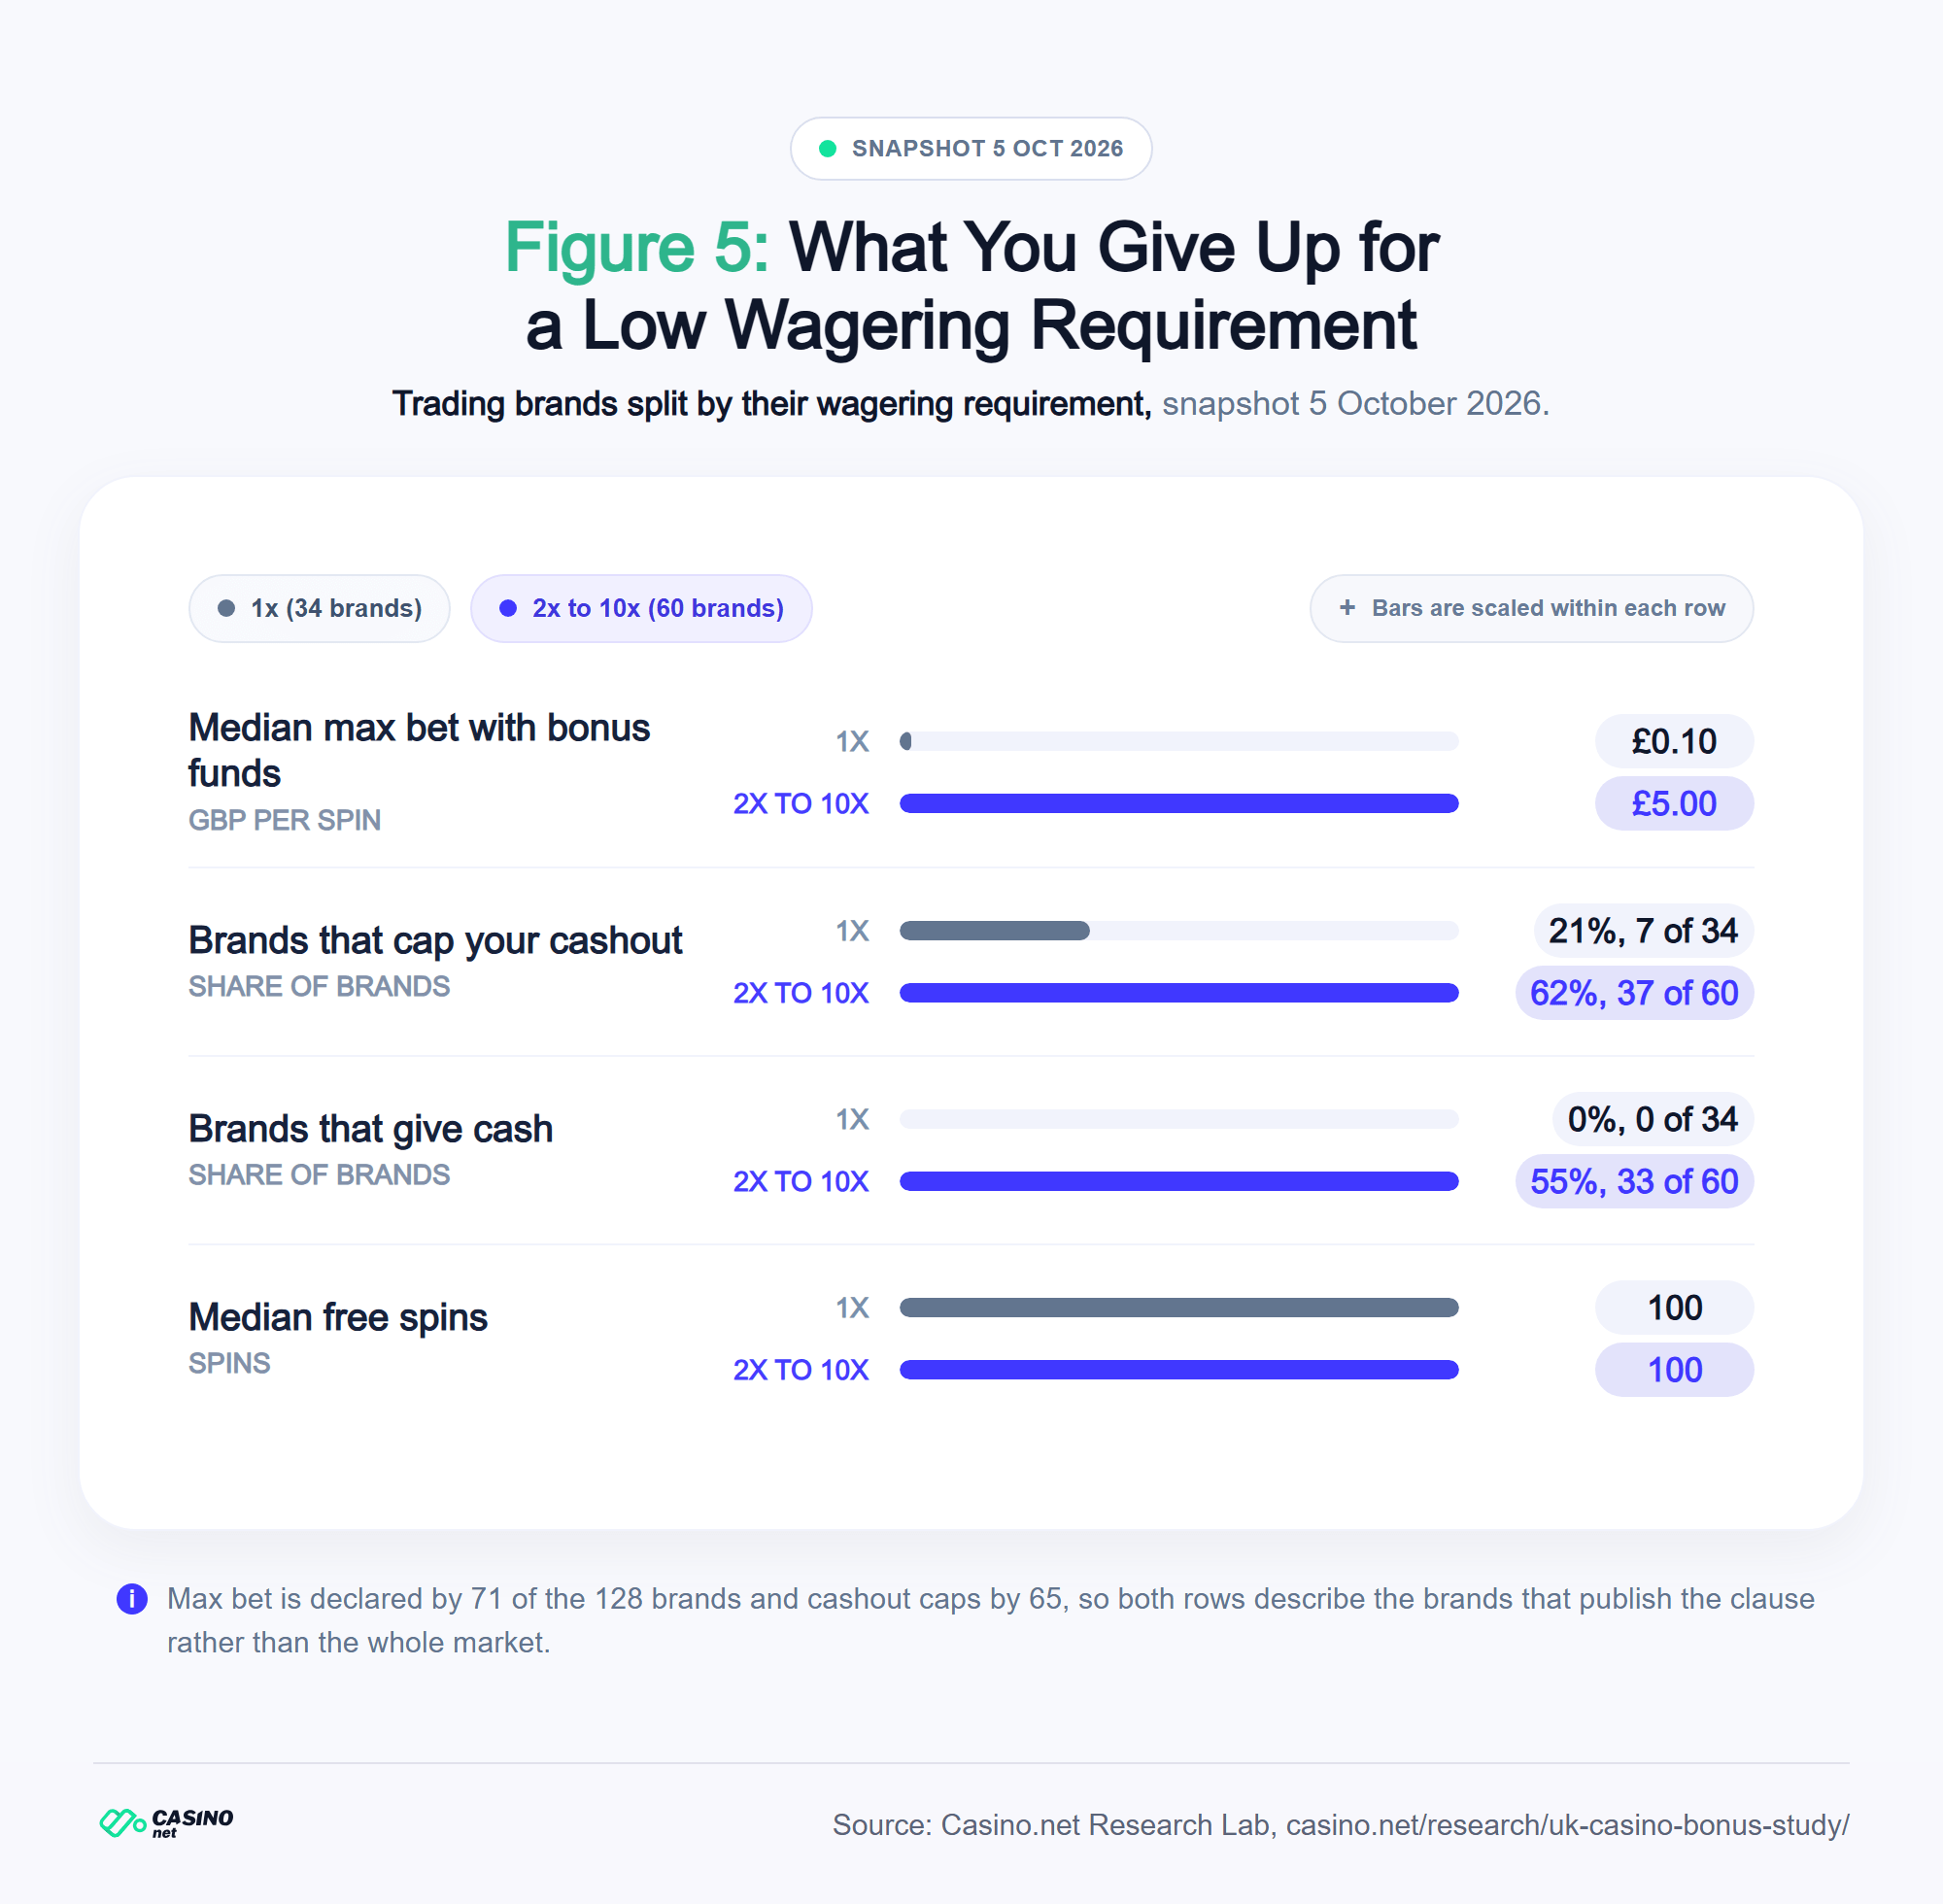
Split the market by wagering and the clearest difference is whether cash appears at all. None of the 34 brands asking 1x includes cash in its headline offer, while 33 of the 60 brands asking between 2x and 10x do. Low wagering is overwhelmingly a spins offer.
Snapshot 5 Oct 2026
Figure 5: What You Give Up for a Low Wagering Requirement
Trading brands split by their wagering requirement, snapshot 5 October 2026.
- Median max bet with bonus funds (GBP per spin): 1x: £5.00, 2x to 10x: £5.00.
- Brands that cap your cashout (Share of brands): 1x: 21%, 7 of 34, 2x to 10x: 62%, 37 of 60.
- Brands that give cash (Share of brands): 1x: 0%, 0 of 34, 2x to 10x: 55%, 33 of 60.
- Median free spins (Spins): 1x: 100, 2x to 10x: 100.
Maximum bets are recorded for seven of the 34 1x brands and 22 of the 60 mid-wagering brands. Both groups have a £5 median; cashout-cap shares use all brands in each group.
The maximum-bet row does not separate the groups: both medians are £5 among the brands that record the clause. The useful difference is in the offer structure and the cashout rules, where the two groups still diverge.
The cashout cap makes that difference clearer. Only 7 of the 34 low-wagering brands cap what you can withdraw, compared with 37 of the 60 mid-wagering brands, whose median cap is £200. Not one of the 34 low-wagering brands puts cash in the offer, against 33 of the 60 mid-wagering ones: in Britain today a 1x offer is, in practice, a spins offer.
What the Recorded Terms Leave Out
The clauses most likely to cost you money are the clauses least likely to be recorded in our database, and four in five bonuses count nothing at the live tables.
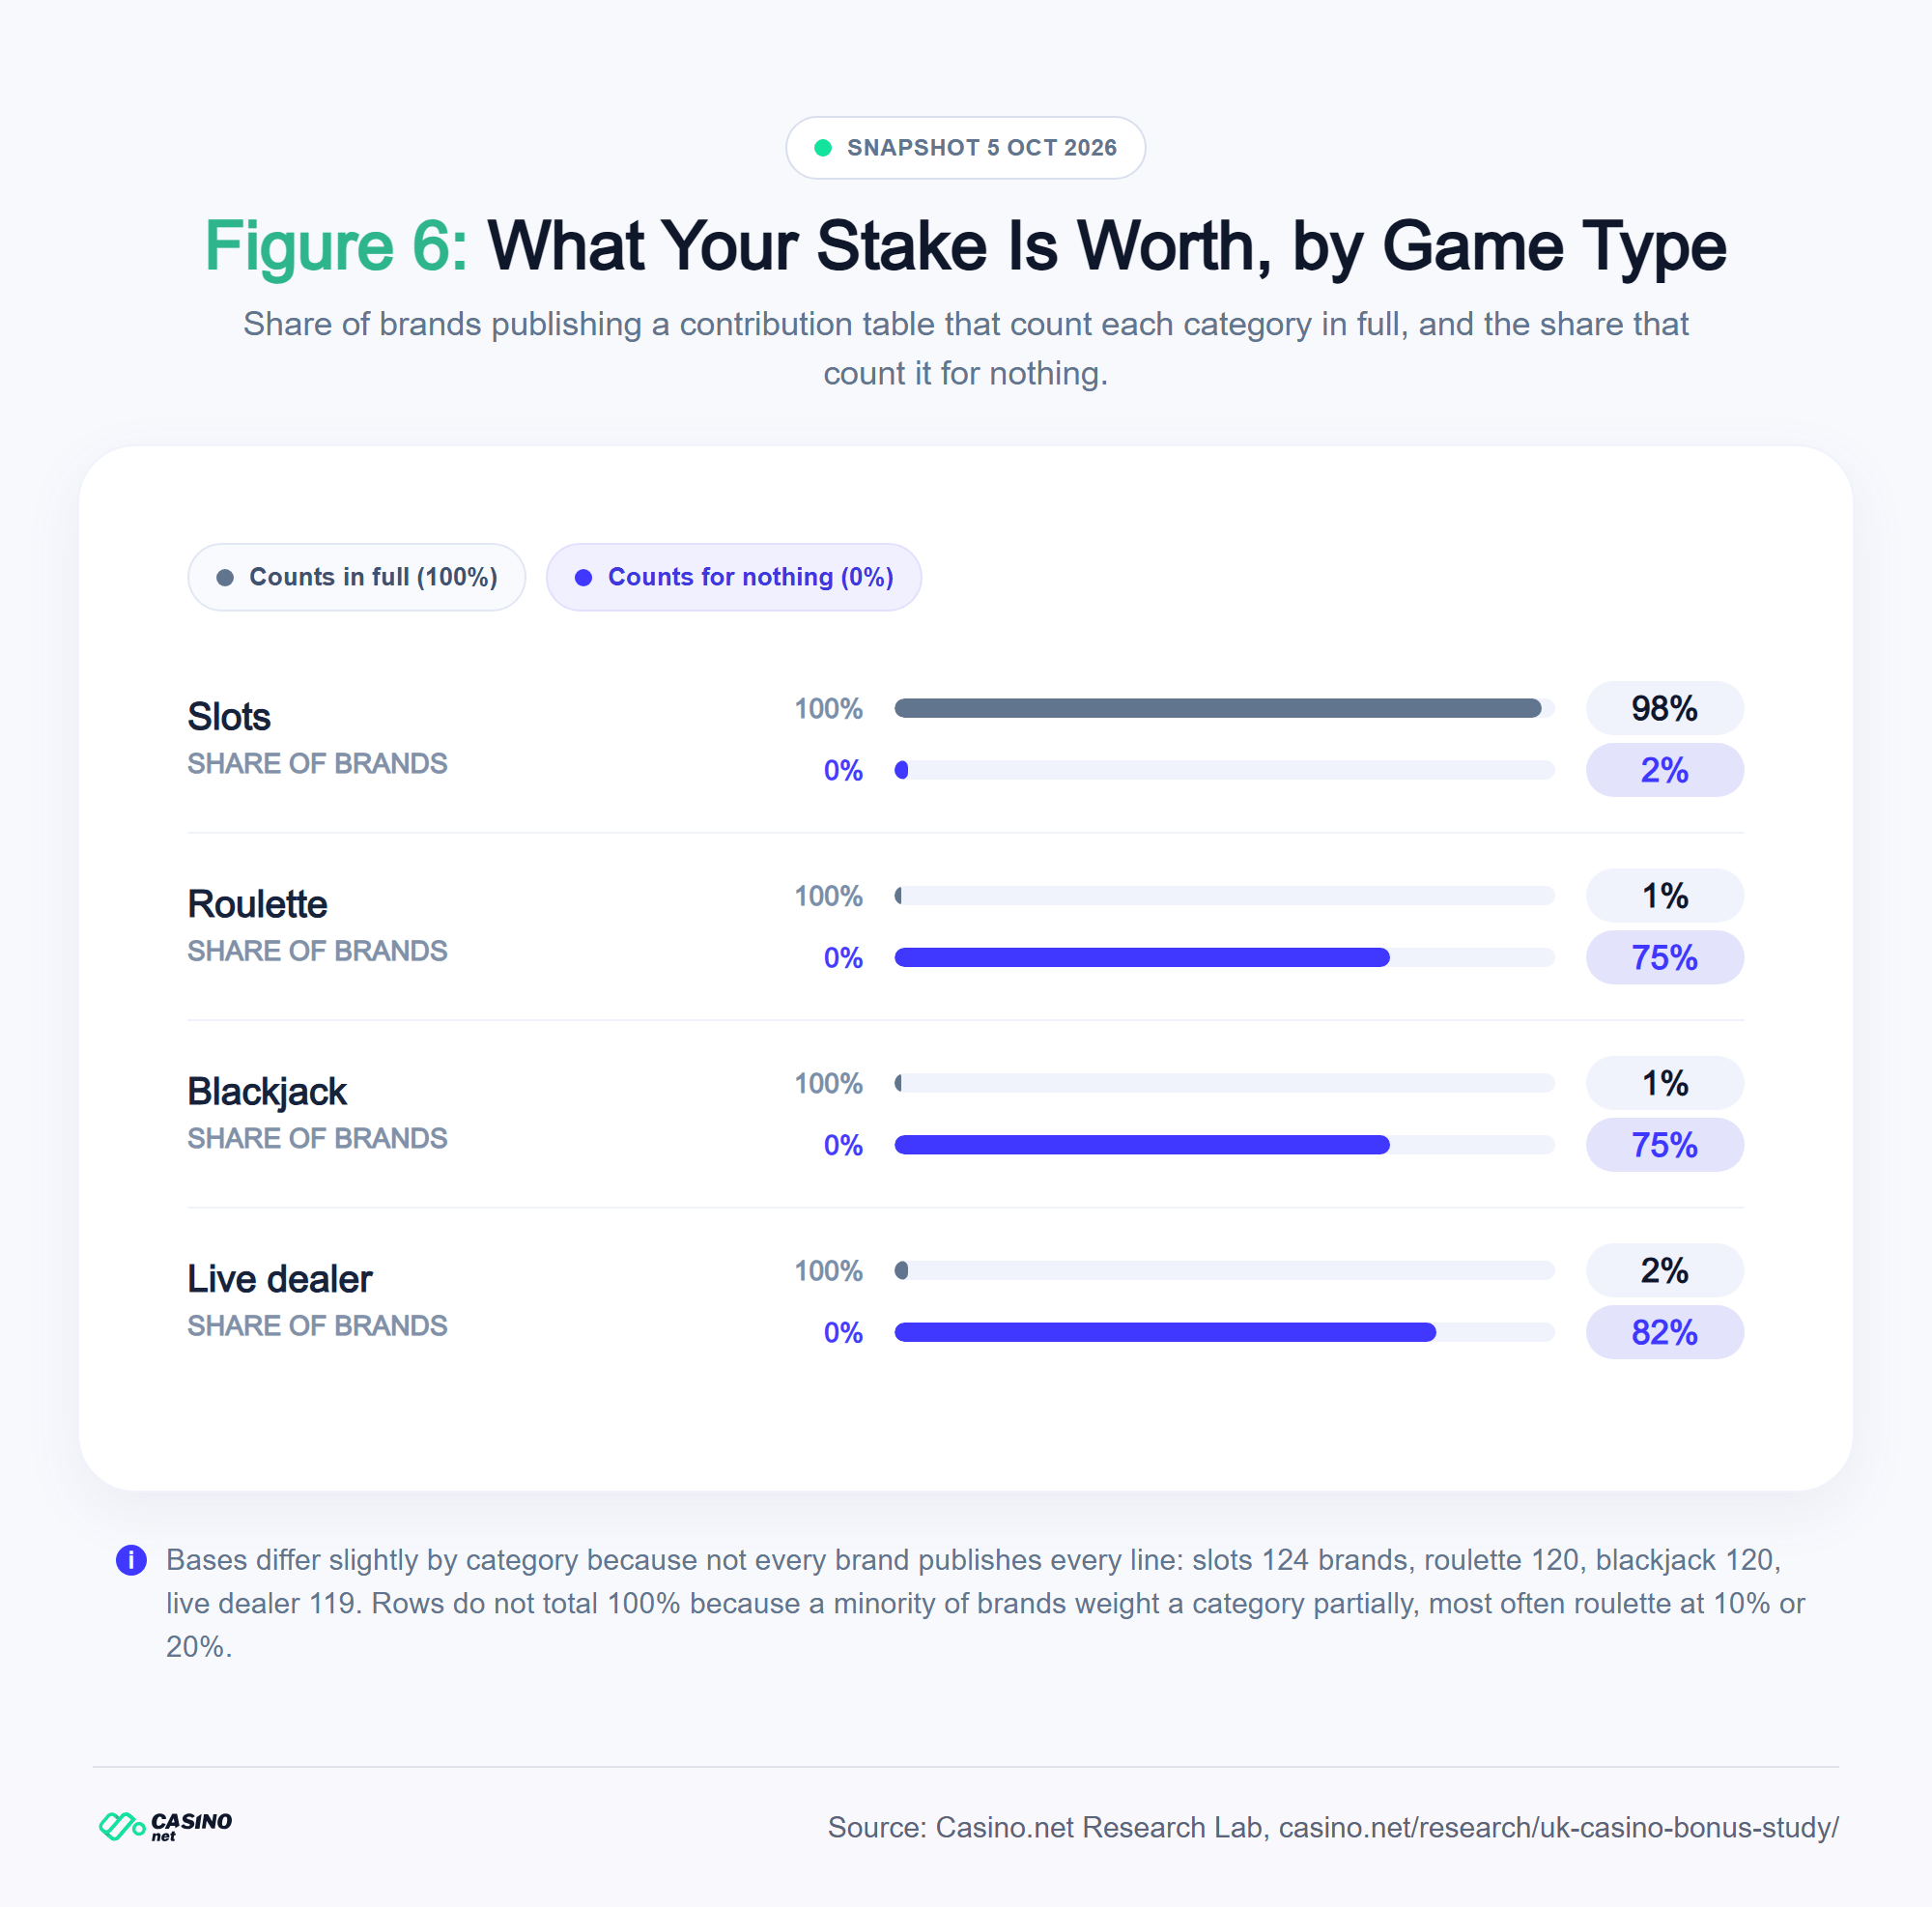
Almost every UK welcome bonus is, in practice, a slots bonus. 122 of the 124 brands with a contribution table recorded count slots at the full 100%, and everything else falls off a cliff: 75% of brands count roulette at zero, 75% count blackjack at zero, and 82% count live dealer games at zero. Not reduced, not weighted, zero.
Snapshot 5 Oct 2026
Figure 6: What Your Stake Is Worth, by Game Type
Share of brands publishing a contribution table that count each category in full, and the share that count it for nothing.
- Slots (Share of brands): Counts in full (100%): 98%, Counts for nothing (0%): 2%.
- Roulette (Share of brands): Counts in full (100%): 1%, Counts for nothing (0%): 75%.
- Blackjack (Share of brands): Counts in full (100%): 1%, Counts for nothing (0%): 75%.
- Live dealer (Share of brands): Counts in full (100%): 2%, Counts for nothing (0%): 82%.
Bases differ slightly by category because not every line is recorded for every brand: slots 124 brands, roulette 120, blackjack 120, live dealer 119. Rows do not total 100% because a minority of brands weight a category partially, most often roulette at 10% or 20%.
This is neither new nor hidden, but it is routinely misread, because “wagering requirement 10x” sounds like a rule about money when it is really a rule about which games you may play for the next few hours. If you are a table player, the honest reading of most British welcome offers is that they are not for you.
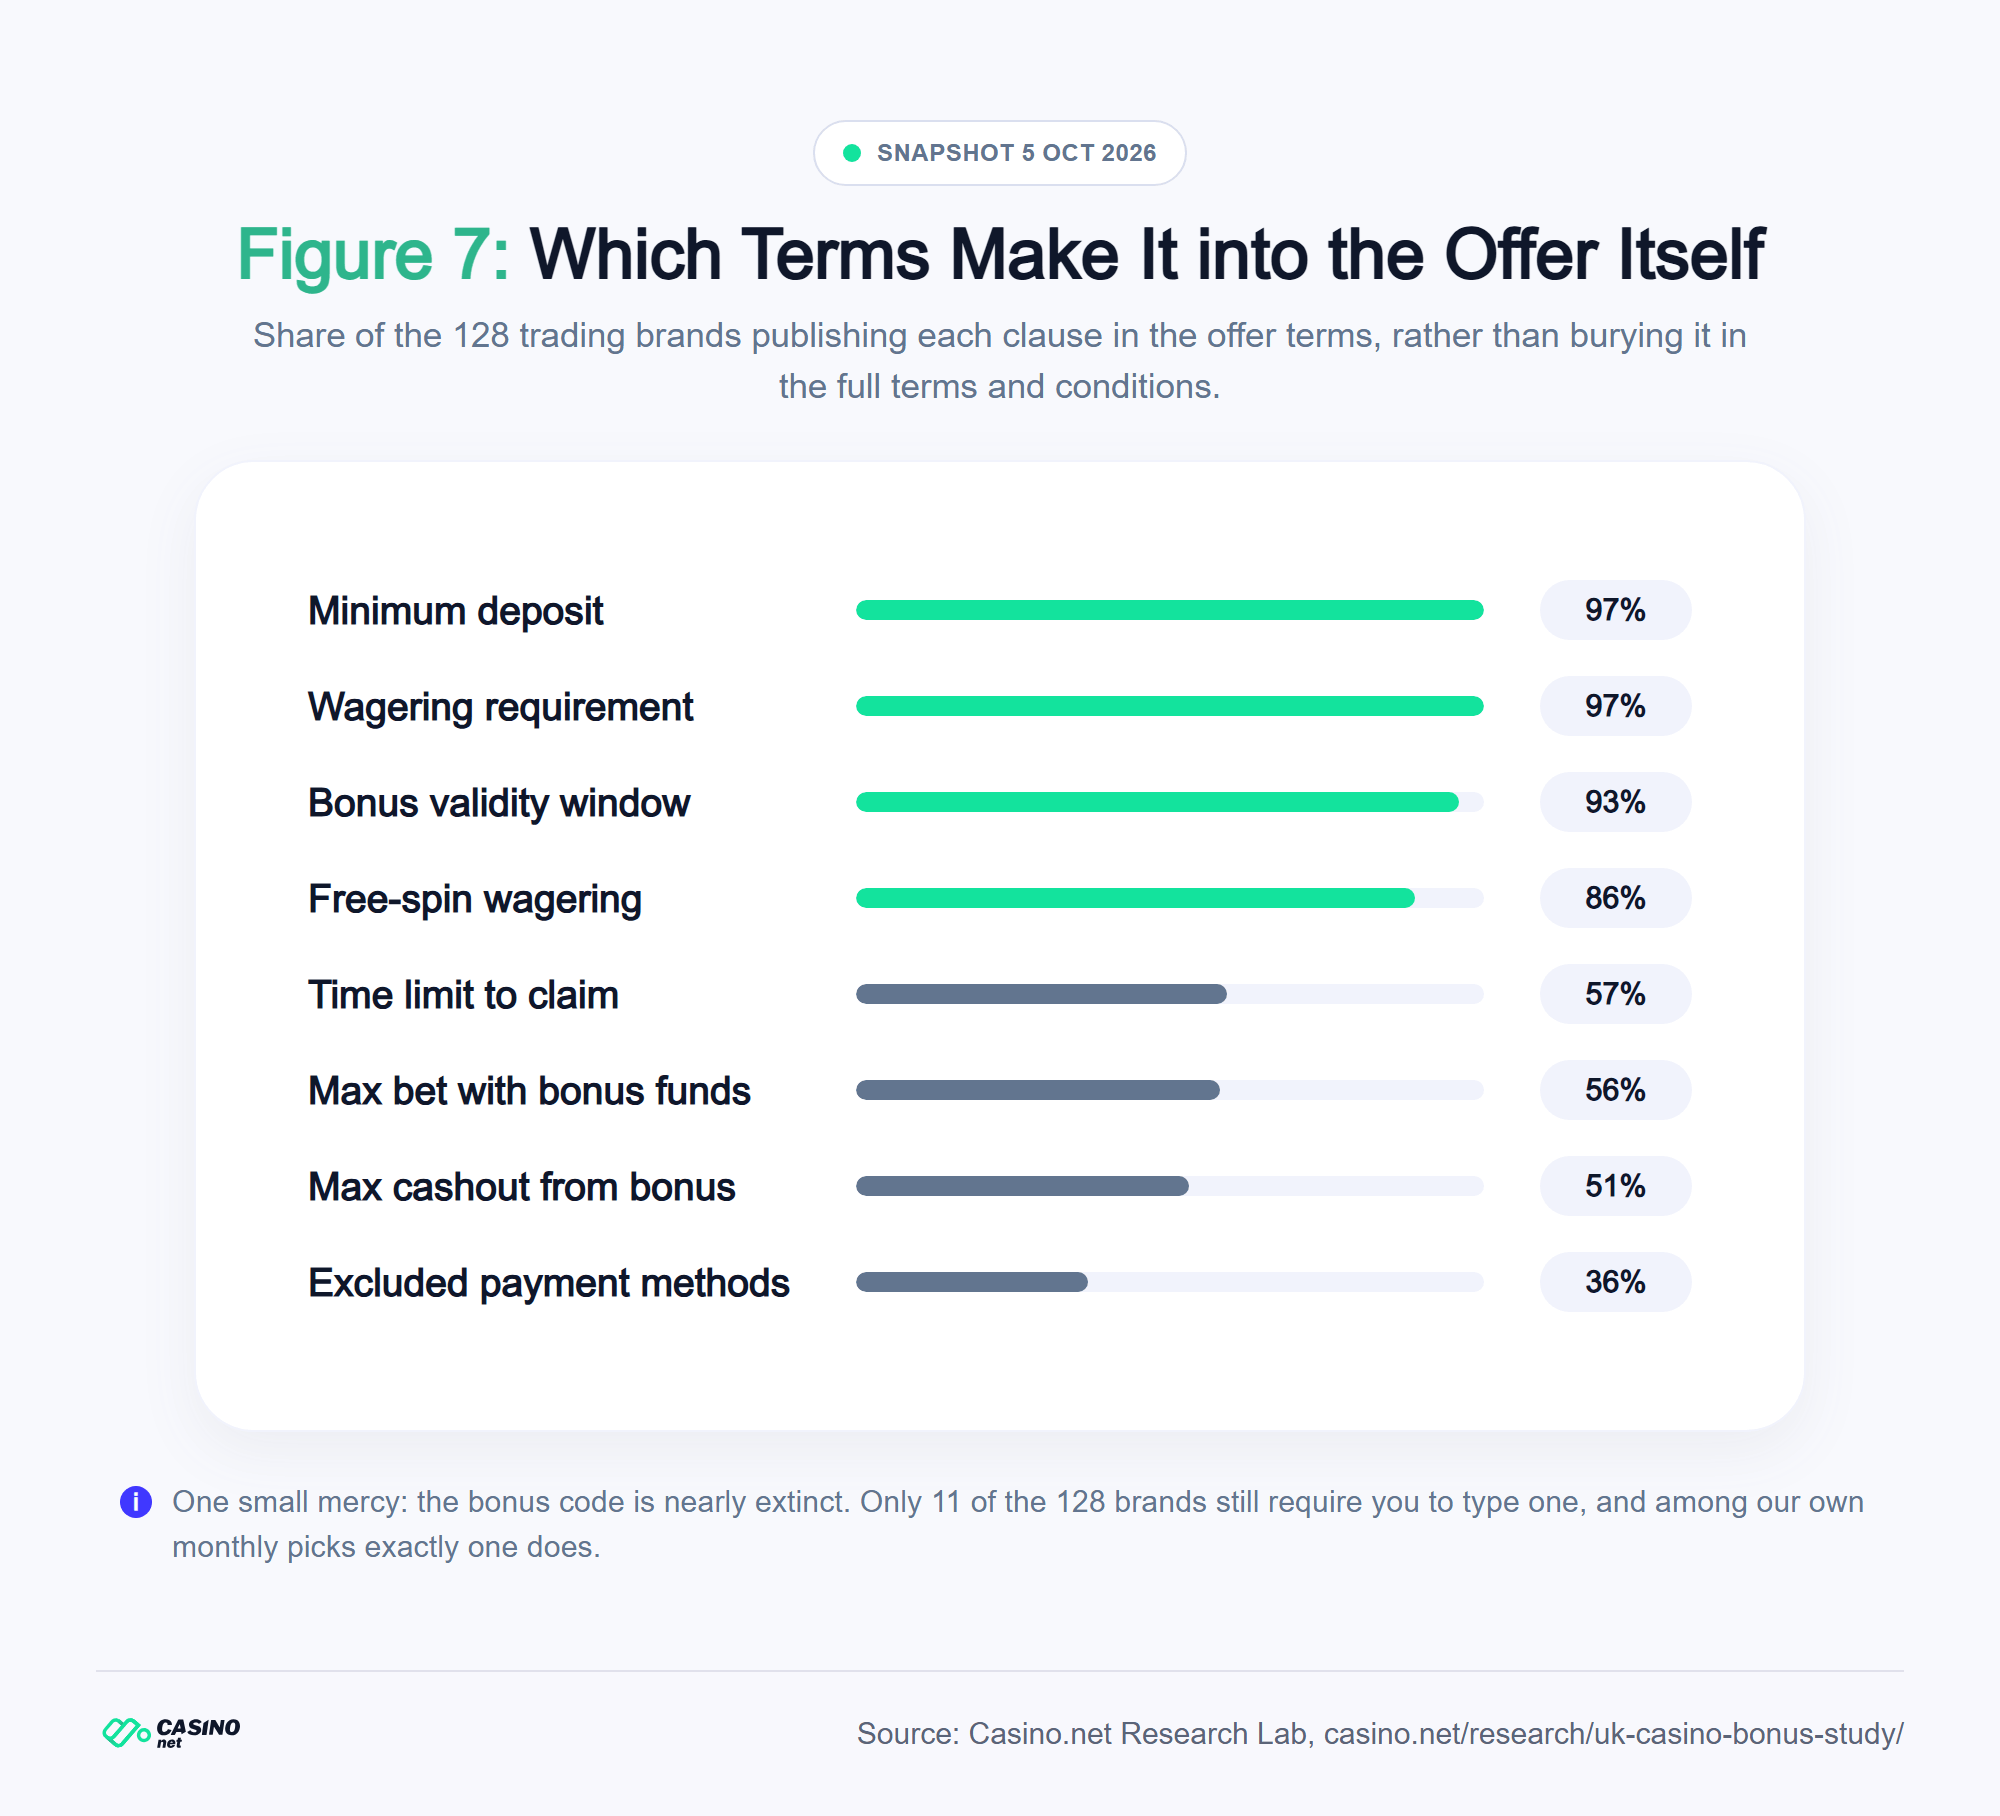
There is a clean and slightly uncomfortable pattern in what our records hold for the British market. The things that make an offer look good are recorded almost universally; the things that can invalidate it are recorded about half the time.
Snapshot 5 Oct 2026
Figure 7: Which Terms Make It into the Offer Itself
Share of the 128 trading brands with each clause recorded in the offer terms, rather than only in the full terms and conditions.
One small mercy: the bonus code is nearly extinct. Only 11 of the 128 brands still require you to type one, and among our own monthly picks exactly one does.
Excluded payments is the one worth dwelling on. Depositing with the wrong method, most often an e-wallet, can void a welcome bonus entirely, and our records show no mention of it in the offer terms for two thirds of British brands. It sits in the full terms and conditions, where few players will find it. Nothing here is a compliance finding. It is a finding about where the friction has been placed.
The one bright spot is length. The median set of short terms in our sample runs to 54 words, genuinely readable and a marked improvement on the paragraph-long blocks that used to be standard. Brands have got better at saying things briefly; they have not, on the whole, got better at saying more of them.
Our Ten UK Picks, Read Against the Study
Our Monthly Picks are chosen by our team on the whole review, not on the bonus, and may reflect commercial partnerships. So they make a useful test: does a list built on other criteria land on the good side of these findings by accident?
Mostly yes, and more sharply than the market average. Seven of our ten UK picks ask for only 1x your deposit, against 27% of the market as a whole, every one of the ten includes free spins, and six attach no wagering whatsoever to the spin winnings.
Our UK Monthly Picks, October 2026: welcome offers as recorded on 5 October 2026.
| # | Brand | Wagering | Cash | Free spins | Spin winnings | Max bet | Min deposit |
|---|---|---|---|---|---|---|---|
| 1 |  |
1x deposit | Not offered | 100 | No wagering | Not listed | £20 |
| 2 |  |
1x deposit | Not offered | 75 | 10x | £5.00 | £20 |
| 3 |  |
1x deposit | Not offered | 100 | No wagering | Not listed | £10 |
| 4 |  |
1x deposit | Not offered | 100 | No wagering | Not listed | £20 |
| 5 |  |
10x | Not offered | 140 | 10x | £2.00 | £25 |
| 6 |  |
1x deposit | Not offered | 100 | No wagering | Not listed | £10 |
| 7 |  |
1x deposit | Not offered | 100 | No wagering | Not listed | £10 |
| 8 |  |
10x dep + bonus | £40 | 100 | 10x | Not listed | £20 |
| 9 |  |
Not listed | Not offered | 140 | 10x | £5.00 | £25 |
| 10 |  |
1x deposit | Not offered | 200 | No wagering | Not listed | £10 |
Ranking is our Monthly Picks order for October 2026, chosen by our team and not on bonus value. Figures recorded 5 October 2026; check the operator’s own terms before claiming.
Only 247Bet records a maximum bet among the seven 1x picks, at £5. The two 10x brands differ: Duelz records £2 and caps the cashout at £100 a day, while Grosvenor has no maximum-bet figure in the study and caps it at £100 on spins and £200 on the bonus. Six of the seven 1x picks leave cashout uncapped.
The list is not spotless, which is rather the point of publishing it. Our records hold no wagering multiple for Los Vegas in the offer terms, putting it in the 9% of the market we could not measure, and Midnite is one of the 11 brands still asking you to type a bonus code. A study that only produced flattering results about our own picks would not be worth running.
How We Built It
The method, and the three things this study cannot tell you.
The sample is every casino brand with a United Kingdom market entry in the Casino.net operator database, read on 5 October 2026: 297 welcome-offer records, once an internal test brand and its six offer rows were discarded. Split by trading status that is 148 offers at 128 trading brands, the sample every headline figure describes, and 124 offers at 64 brands marked closed or withdrawn, the 56 fully closed ones with usable terms forming the shadow cohort in Figure 1. Where a brand runs a multi-deposit package we take the first-deposit offer as its headline and count the brand once.
Free-text fields were normalised before counting. “None”, “N/A”, “Not listed”, a dash and an empty string are treated as unavailable in the published aggregates, rather than as zero. That does not prove they share the same real-world meaning: a brand with no recorded max-bet figure is not a brand with a zero or unlimited max bet.
- It is a snapshot, not a feed. Bonus terms change weekly. Every number here describes 5 October 2026 and nothing after it. For live offers, use our ranked list of UK casinos.
- Some records may lag the operator. A figure above the 10x cap can mean a licensee in breach or a stale record on our side. Records above the cap are checked by hand against the operator’s own terms; two are still queued.
- Two cohorts, not one timeline. The comparison sets brands that left the market against brands that remained. It is a cross-sectional signal, not a controlled experiment or a record of how individual offers changed.
Scores and rankings referenced on this page come from the Casino.net rating algorithm, which is published in full and does not use bonus size as an input.
Definitions Used Throughout This Study
Wagering requirement
How many times the bonus amount must be staked before winnings can be withdrawn. Since 19 January 2026, UKGC licence condition SR 5.1.1(3a) caps this at 10x for British licensees.
Trading brand
A brand whose UK market entry is marked active in our database on the snapshot date. Brands marked closed, withdrawn or temporarily removed are excluded from every headline figure and appear only in the exited cohort in Figure 1.
Wager-free
Winnings are paid as cash with no staking requirement attached. Applied separately to bonus funds and to free-spin winnings, which are governed by different terms and, in the case of spin winnings, are not covered by the 10x cap.
Contribution
The share of a stake on a given game type that counts toward clearing the wagering requirement. Zero means stakes on that game do not advance the bonus at all.
For Journalists and Researchers
You’re welcome to use these findings in your reporting or research. Both files come from the 5 October 2026 snapshot behind every figure on this page.
Download The Dataset (CSV) · Download The Figures (CSV)
Dataset: one headline offer per brand, trading and exited, with brand names removed. Figures: every value charted on this page.
- Reuse licence: CC BY 4.0
- Credit: Casino.net Research Lab
- Data snapshot: 5 October 2026
- Questions and corrections: editorial@casino.net
Charts to Share
All seven figures as high-resolution PNGs, branded and sourced, ready to embed with attribution.
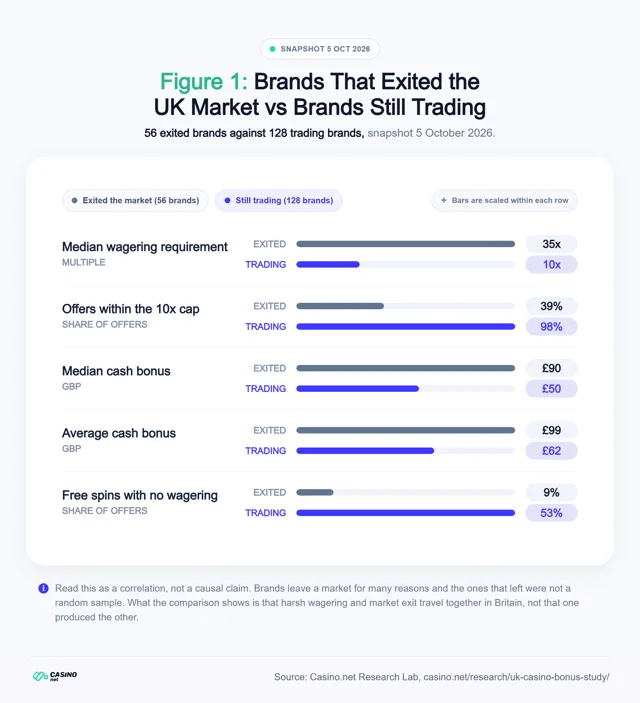 Figure 1: Brands That Exited the UK Market vs Brands Still Trading. Download PNG
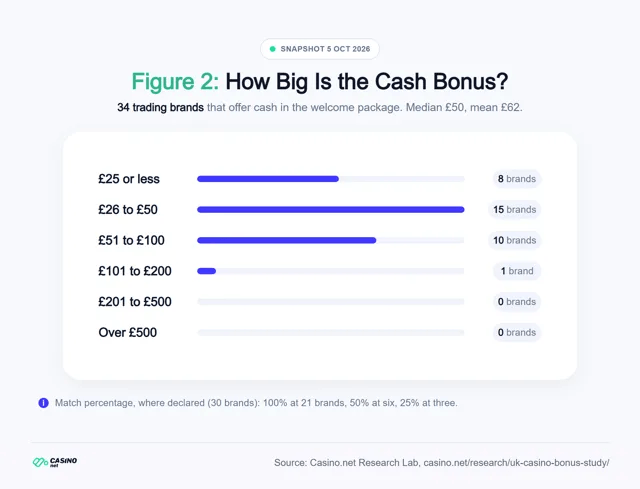 Figure 2: How Big Is the Cash Bonus?. Download PNG
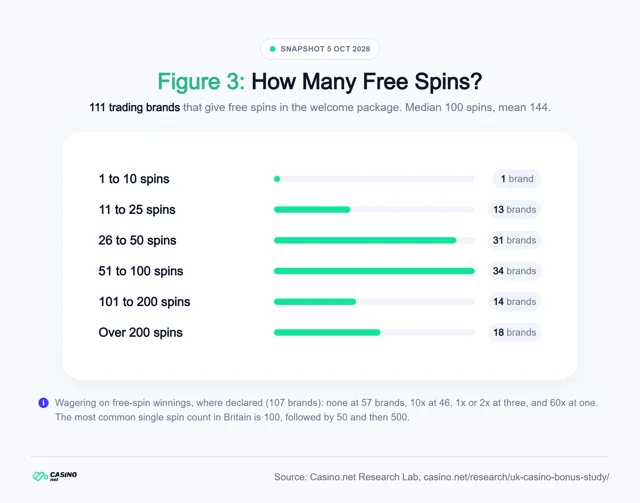 Figure 3: How Many Free Spins?. Download PNG
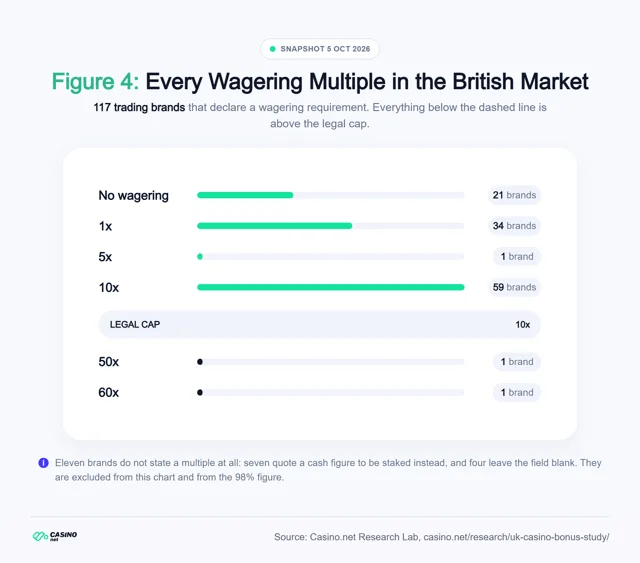 Figure 4: Every Wagering Multiple in the British Market. Download PNG
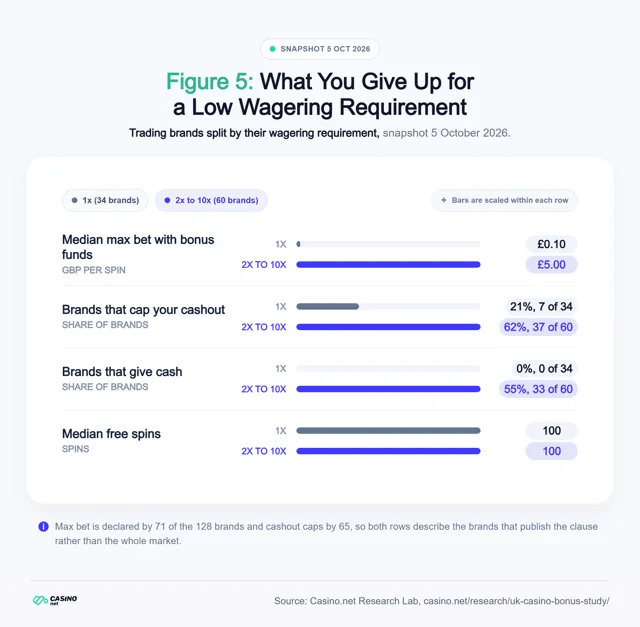 Figure 5: What You Give Up for a Low Wagering Requirement. Download PNG
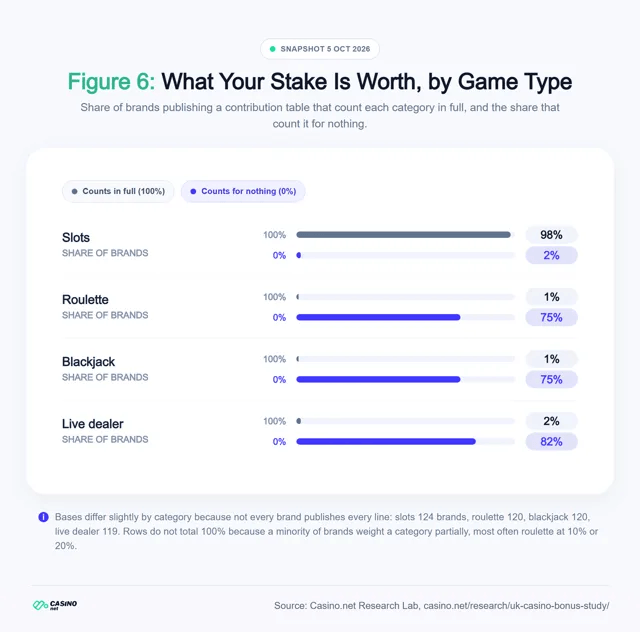 Figure 6: What Your Stake Is Worth, by Game Type. Download PNG
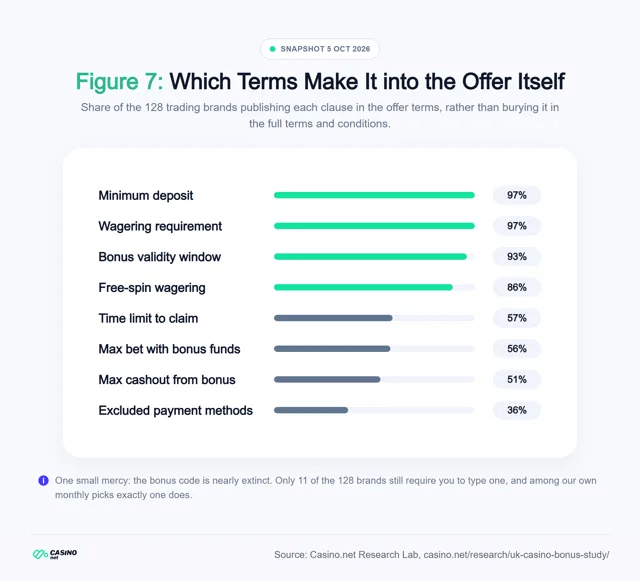 Figure 7: Which Terms Make It into the Offer Itself. Download PNG
Using This Research
Free to reproduce, in full or in part, with attribution under CC BY 4.0.
UK Casino Bonus Study, Edition 01. Data snapshot 5 October 2026. Published by the Casino.net Research Team, part of the Casino.net Research Lab, which also publishes research on how long casinos let players self-exclude, research on recorded casino withdrawal estimates and a global online casino laws atlas. Figures are frozen at the snapshot date. Any later correction is dated on this page. Nothing on this page is an offer, and no bonus described here is available through it; see our UK casino rankings for current offers. Full terms and conditions apply at every operator.
Gamble Responsibly
18+ only. Gambling can be addictive. Free confidential help and self-exclusion tools are available to anyone in Britain, and the licence conditions referenced on this page are published by the Gambling Commission.
- Fix your budget first, then look at the offer. A bonus should fit inside that budget, never stretch it.
- A wagering requirement is a condition, not a discount. Work out how much play it asks for before you deposit.
- Do not top up just to finish clearing a bonus. Walk away and keep what is left.
- If you hide how much you play or borrow to keep going, contact one of these free services.
- GambleAware: Free, confidential advice and treatment for anyone in Britain.
- GAMSTOP: One sign-up excludes you from every UK-licensed gambling site at once.
- BetBlocker: Free software that blocks gambling sites on your own devices.